Many buyers ask, “can expandable houses be financed?” The answer is often yes, but approval depends on the house, lender, and intended use. An expandable home may arrive compact, then open into larger living areas through hinged walls, sliding sections, or modular additions. That unusual design can make financing less straightforward than financing a conventional property.
This guide examines ten practical funding options, including construction loans, personal loans, manufacturer financing, credit union programs, and specialized modular-home lenders. Each option has different requirements. Lenders may review your credit history, income, deposit, land ownership, building plans, transport costs, foundation design, and utility connections. A detailed appraisal may also be difficult when few comparable homes exist nearby.
Ask questions early.
A lender may treat the unit as a vehicle, manufactured home, modular home, or permanent residence. That classification can change the interest rate, loan term, insurance requirements, and required documentation. Local building approval matters too. Do not rely only on a manufacturer’s estimate; request independent cost figures for delivery, site preparation, installation, permits, and future expansion.
The financing process can feel practical one day and confusing the next. Some lenders understand innovative housing well, while others remain cautious. This guide does not promise approval. Instead, it compares realistic pathways and highlights important gaps buyers sometimes overlook. With verified documents, a clear budget, and professional advice, you can approach lenders with stronger evidence and fewer surprises.
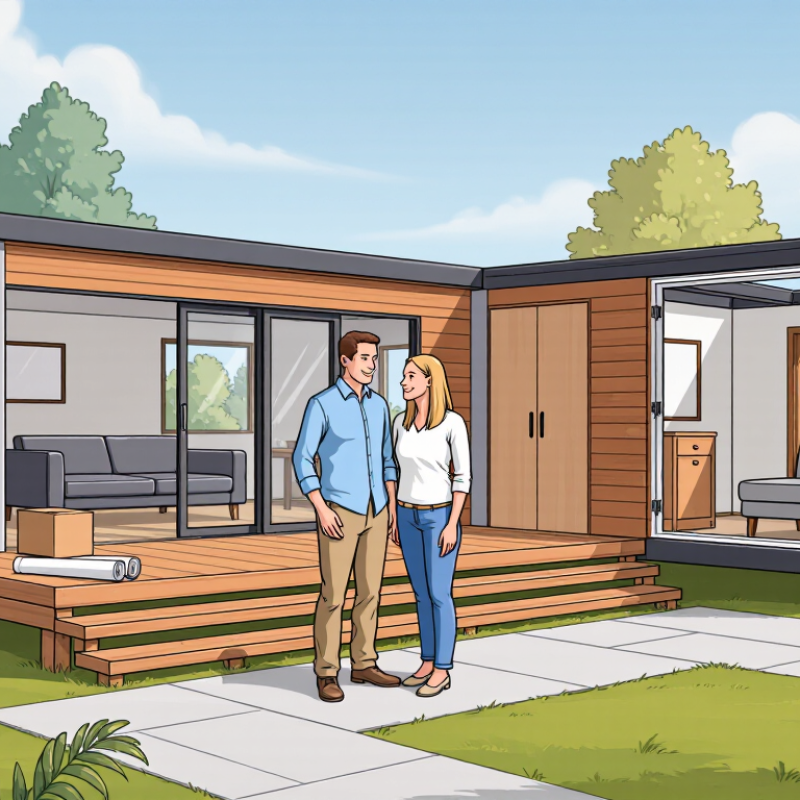
Expandable houses are compact homes that grow after delivery. During transport, their walls, floors, or rooms remain folded inside a smaller frame. On site, trained workers extend the structure using hinges, rails, hydraulic systems, or manual supports. The process can create a bedroom, living area, or wider kitchen within hours or days. Connections for electricity, plumbing, drainage, and internet still require careful planning.
The design works because the home separates transport size from living size. Its steel frame or engineered panels carry loads while movable sections lock into position. However, performance depends on foundation quality, weather sealing, insulation, and installation accuracy. A lower purchase price does not always mean lower project costs. Delivery, land preparation, permits, utility work, and maintenance can change the budget quickly. The category is still unfamiliar, so lender requirements may vary.
Tips: Ask for structural drawings, installation records, warranty terms, and a detailed site-cost estimate. Compare savings, construction loans, personal loans, home-equity loans, credit-union loans, mortgage financing, renovation loans, government-backed programs, seller financing, and staged payment plans. Confirm whether the lender treats the house as movable property or real estate. That classification can affect interest rates and approval requirements. Keep emergency funds available. A delayed foundation or missing utility connection can interrupt the schedule, even when the house itself arrives on time.
Expandable houses often cost between $60,000 and $180,000 before land, taxes, and site work. Installation may add $30,000 to $120,000, depending on transport distance, foundation type, labor, and utility connections. A compact unit on a prepared lot can remain near the lower range. Rocky ground, steep access, or distant water lines can increase the bill quickly.
Ask for an itemized quotation. Not just a headline price. Confirm whether it includes delivery, crane service, insulation, plumbing, electrical work, permits, appliances, and final inspections. A reinforced foundation may cost $10,000 to $35,000, while utility connections can add several thousand dollars. These figures vary by region, so local contractor estimates matter more than online averages.
Financing usually depends on how lenders classify the house. A completed home with a permanent foundation may qualify for a mortgage or construction loan. A movable unit may require personal-property financing, which can mean shorter terms and higher payments. Compare the total repayment, not only the monthly figure. I once treated site preparation as a minor expense; that assumption was too optimistic. Keep a 10% to 20% contingency reserve. It feels excessive until a delayed permit or drainage problem appears. Independent inspections and written payment stages can reduce surprises.
Financing an expandable house begins with its legal classification. Is it real property, a manufactured home, or a movable unit? Lenders inspect the foundation, land ownership, transport system, and installation plans. A permanent foundation may support a construction-to-permanent mortgage. This option can combine building costs and long-term repayment in one loan.
A personal-property loan may suit an expandable unit without owned land. However, the Consumer Financial Protection Bureau reports that chattel loans usually have higher rates and shorter terms than mortgages. That difference can make monthly payments feel manageable while increasing total interest. Read the repayment schedule carefully. Small print matters.
Home-equity loans and cash-out refinancing may help owners who already have substantial property value. Government-backed manufactured-housing programs can provide another route, depending on location, foundation standards, and borrower qualifications. The Federal Housing Finance Agency reported that the average 30-year mortgage rate reached about 6.8% during 2023, showing why rate changes deserve serious attention. Credit unions, construction lenders, and specialized housing lenders may also consider staged payments tied to factory delivery and site installation. Ask who pays if delivery is delayed. That risk is easy to overlook. Independent appraisals, engineering documents, insurance estimates, and written installation contracts can strengthen an application, though approval is never automatic. A practical mistake is comparing only monthly payments instead of total borrowing costs.
Can Expandable Houses Be Financed? Top 10 Options
Lenders review expandable house loans differently from standard home mortgages. They examine the land, foundation, transport history, and final installation plan. The structure must have a clear value after expansion. Appraisers may struggle when comparable homes are limited. That uncertainty can affect approval, interest rates, and required deposits. Lenders also check income, credit history, debt levels, insurance availability, and local building approvals. A missing document can delay the entire application.
Tips: Prepare the purchase contract, land title, construction drawings, contractor details, and realistic cost estimates. Ask whether the lender accepts modular, manufactured, or movable structures. Confirm when loan funds are released. Some lenders require inspections before each payment. Do not guess here.
Possible financing routes include construction loans, standard mortgages, personal loans, land loans, home-equity borrowing, and specialist manufactured-home financing. Each option measures risk differently. A construction lender may focus on the build schedule and contractor qualifications. A mortgage lender may focus more heavily on permanent foundations and resale evidence. A personal loan may move faster, but its shorter term can increase monthly payments. This is where many buyers miscalculate affordability. The lowest upfront hurdle may create the highest long-term cost.
A careful applicant should request written terms, including fees, valuation rules, insurance requirements, and early repayment conditions. Local standards can also change the lender’s decision. Speak with a qualified loan professional and an independent property appraiser before signing. The strongest application is detailed, realistic, and easy to verify.
The chart compares common financing paths by their typical upper-end term. Lenders also review credit history, verified income, debt-to-income ratio, down payment, appraisal, title status, transportability, foundation type, and whether the expandable house is classified as real property or personal property.
Terms shown are commonly available upper-end terms and are not guaranteed offers. Actual eligibility depends on the borrower, property classification, location, condition, installation method, and lender underwriting rules. A cash purchase has no loan term.
Financing an expandable house starts with its legal classification. A lender may treat it as real property, a manufactured home, or personal property. That choice changes the rate, term, down payment, and security required. The Consumer Financial Protection Bureau’s manufactured-housing finance report found that chattel loans typically carry higher rates and shorter terms than mortgage loans. Ask for both annual percentage rate and total repayment. A low monthly payment can hide a costly 15-year agreement.
Compare the details line by line. Check whether the loan covers delivery, foundation work, permits, installation, and utility connections. These expenses can arrive before the house is usable. The U.S. Census Bureau reported about 89,500 manufactured homes shipped in 2023, showing a substantial market but not uniform financing standards. Request written quotes from at least three lenders. Keep the comparison sheet beside your calculator. Short sentences help.
A fixed-rate mortgage may offer predictable payments, while a variable-rate product can create pressure after an introductory period. Review late fees, early-repayment charges, appraisal rules, and insurance requirements. Confirm whether the lender accepts expandable construction as collateral before paying application fees. Fannie Mae’s manufactured-housing guidance emphasizes permanent foundations and compliant land ownership for mortgage eligibility. That detail can change everything. I would not compare rates alone. I have seen borrowers focus on the monthly figure, then discover that site work was excluded. Some financing decisions still feel unclear, so an independent housing counselor or licensed attorney should review unusual terms before signing.
| Financing Option | Typical Loan Amount | Indicative Rate Structure | Typical Term | Typical Down Payment or Equity | Approval Requirements | Funding Speed | Best Suited For | Main Advantages | Important Risks or Limitations |
|---|---|---|---|---|---|---|---|---|---|
| 1. Cash Purchase | Full purchase price, commonly from approximately $20,000 to $150,000 or more depending on size, specifications, delivery, and site work. | No interest | Immediate ownership; no repayment period | 100% paid at closing | Proof of funds and a purchase contract | Same day to several days | Buyers with sufficient savings who want to avoid borrowing costs | Lowest total cost; no credit underwriting; flexible resale and use | Uses a large amount of cash and may leave less money for foundations, utilities, permits, and site preparation. |
| 2. Unsecured Personal Loan | Approximately $5,000 to $100,000, subject to income, credit, and lender limits | Usually fixed APR; often about 8%–36% for qualified borrowers | 2–7 years | Usually 0%; no property collateral | Credit score, debt-to-income ratio, income verification, and bank statements | One day to two weeks | Smaller purchases, deposits, transport costs, or buyers without home equity | Fast application; no lien on the house or land; predictable payments with a fixed rate | Short terms can create high monthly payments; rates may be higher than secured financing. |
| 3. Home Equity Loan | Often up to 75%–85% of home value minus the existing mortgage balance, subject to underwriting | Usually fixed APR; commonly lower than unsecured borrowing | 5–30 years | Equity is required; lenders may limit combined loan-to-value to about 75%–85% | Home appraisal, stable income, acceptable credit, mortgage history, and sufficient equity | Two to six weeks | Homeowners who want a lump sum for the expandable house and related site work | Fixed payments; potentially lower rate; suitable for a defined project budget | The primary residence secures the debt, so missed payments can create foreclosure risk. |
| 4. Home Equity Line of Credit | Often up to 75%–85% of home value minus existing liens | Usually variable APR tied to a benchmark rate plus a margin | Commonly 10-year draw period plus a 10–20-year repayment period | Available home equity is required | Credit review, appraisal, income verification, and acceptable debt-to-income ratio | Two to six weeks | Projects with uncertain costs, including installation, foundations, and utility connections | Borrow only what is needed; reusable credit during the draw period | Payments and total interest can rise when rates increase; the home secures the line. |
| 5. Cash-Out Mortgage Refinance | New mortgage balance minus the existing mortgage payoff, usually within a lender’s maximum loan-to-value limit | Fixed or adjustable mortgage rate; pricing depends on credit, loan-to-value, and market conditions | Typically 15–30 years | Often requires at least 15%–25% remaining home equity, depending on the program | Full mortgage underwriting, appraisal, income verification, title review, and closing documentation | Four to eight weeks or longer | Homeowners with substantial equity who prefer one consolidated mortgage payment | May provide a larger amount and spread repayment over a long term | Closing costs may be significant; extending the mortgage term can increase lifetime interest. |
| 6. Construction-to-Permanent Loan | Project cost or completed value, including eligible land, materials, labor, permits, and site improvements | Construction-phase rate may be variable; permanent phase may be fixed or adjustable | Construction period of about 6–18 months, followed by a 10–30-year mortgage | Often 10%–25%, depending on the project and borrower profile | Approved plans, budget, construction contract, inspections, permits, land documentation, and an eligible builder or installer | One to three months before initial funding | New installations on owned land where the expandable house will become a permanent improvement | Can combine construction expenses and long-term financing; may fund in progress payments | Difficult if the unit is treated as movable personal property or lacks approved plans and permanent utility connections. |
| 7. Manufactured or Modular Home Mortgage | Purchase price plus eligible land, foundation, delivery, and installation costs | Mortgage-style fixed or adjustable rate; depends on property classification and borrower qualification | Commonly 15–30 years | Often 5%–20%; may be higher for leased land or nonstandard installations | Unit must meet applicable building standards, be legally titled, and usually be permanently affixed to owned land | Four to ten weeks | Expandable houses that qualify as real property after permanent installation | Longer repayment period and potentially lower cost than unsecured borrowing | Financing can be unavailable if the house remains movable, sits on leased land, or lacks required certifications. |
| 8. Chattel or Personal-Property Loan | Commonly $20,000 to $150,000, depending on the unit, borrower, and collateral value | Usually fixed APR; often higher than a conventional real-property mortgage | 5–20 years | Often 5%–20%; lender requirements vary | Unit identification, purchase invoice, insurance, income verification, and credit review | One to six weeks | Units that remain movable or are located on leased land | Designed for personal property; may not require land ownership or a traditional mortgage appraisal | Higher rates, shorter terms, and faster depreciation may result in a larger payment and less favorable resale economics. |
| 9. Dealer or Manufacturer Installment Financing | Usually covers the unit price and may include selected delivery or installation charges | Fixed APR; promotional pricing may be available, but compare the total cost carefully | Typically 3–15 years | Often 0%–20%, depending on credit and the transaction | Credit application, verified income, purchase agreement, and acceptable debt-to-income ratio | Same day to several weeks | Buyers seeking a convenient point-of-sale application for a standard model | Simple application process; may coordinate financing with the purchase and delivery schedule | Optional products, documentation charges, prepayment rules, and bundled site costs can increase the actual cost. |
| 10. Bridge Loan or Asset-Based Financing | Based on available home equity or another asset; amount varies by collateral value and lender policy | Usually variable or short-term fixed pricing; commonly higher than a permanent mortgage | 6–36 months | Substantial equity or acceptable collateral is generally required | Asset valuation, exit strategy, proof of repayment source, credit review, and income or liquidity evidence | Two to six weeks | Time-sensitive purchases before selling another property or arranging permanent financing | Can provide temporary funds when a standard mortgage is not ready | Short maturity, variable costs, extension fees, and balloon repayment risk make permanent refinancing essential. |
| Comparison note: Expandable-house financing depends heavily on whether the unit is classified as real property, a manufactured or modular home, an RV, or personal property. Before applying, confirm the required foundation, permits, building-code compliance, title status, insurance, delivery cost, utility work, and whether the lender finances the complete project rather than only the structure. Rate ranges and terms are indicative market ranges, not guaranteed offers; compare APR, origination fees, closing costs, collateral requirements, total interest, prepayment rules, and the full monthly payment. | |||||||||
It is a compact home that expands after delivery. Folded walls, floors, or rooms fit inside a smaller transport frame. On site, workers extend the structure within hours or days. Small footprint, larger interior.
Hinges, rails, hydraulic systems, or manual supports move the folded sections outward. Workers then lock the structure into position. The process may create bedrooms, living spaces, or wider kitchens. Installation accuracy matters greatly.
Electricity, plumbing, drainage, and internet connections need careful coordination. The foundation must be ready before delivery. A missing utility connection can stop the schedule. The house may arrive on time, but the project can still wait.
The purchase price is only one part of the budget. Land preparation, delivery, permits, utility work, foundation construction, and maintenance add costs. A low quote can mislead buyers. Keep emergency funds available.
Yes, but financing depends on its legal classification. A lender may treat it as real property, a manufactured home, or movable property. Each category has different approval rules. Not always simple.
Possible choices include construction loans, standard mortgages, personal loans, land loans, and home-equity borrowing. Specialist housing finance may also be available. Staged payments can match factory delivery and site installation. Compare total borrowing costs, not only monthly payments.
Prepare the purchase contract, land title, structural drawings, installation plans, and contractor details. Lenders may also request insurance estimates and realistic site costs. Missing paperwork can delay approval. Do not guess.
Comparable homes may be limited, making valuation harder. Lenders may question resale value, foundation quality, and final installation standards. Local approvals and insurance availability also matter. The category remains unfamiliar in some areas.
Request written terms covering interest, fees, inspections, insurance, and early repayment conditions. Confirm when funds are released. Ask who pays if delivery is delayed. I might overlook that risk without a written answer.
Do not judge affordability by the smallest monthly payment. A shorter loan term may cost more each month. A longer term may increase total interest. Review the complete repayment schedule carefully. Small print matters.
Expandable houses are prefabricated or modular homes designed to arrive in a compact form and expand into a larger living space after delivery. Their design can reduce construction time and may offer flexibility for homeowners, guest accommodations, offices, or rental use. However, total expenses include the purchase price, transportation, site preparation, utility connections, foundation work, installation, permits, and interior finishing. Understanding the complete budget is essential before applying for funding.
The question “can expandable houses be financed” depends on the property’s construction quality, legal classification, land ownership, resale potential, and whether it is treated as real estate or a movable structure. Potential options may include personal loans, home improvement loans, construction financing, mortgages, equipment-style lending, or financing arranged through a qualified seller. Lenders commonly review credit history, income, debt levels, down payment, property documents, installation plans, and insurance requirements. Comparing interest rates, fees, repayment periods, collateral rules, and early-payment conditions can help buyers choose a suitable and manageable financing solution.

Cencal Home